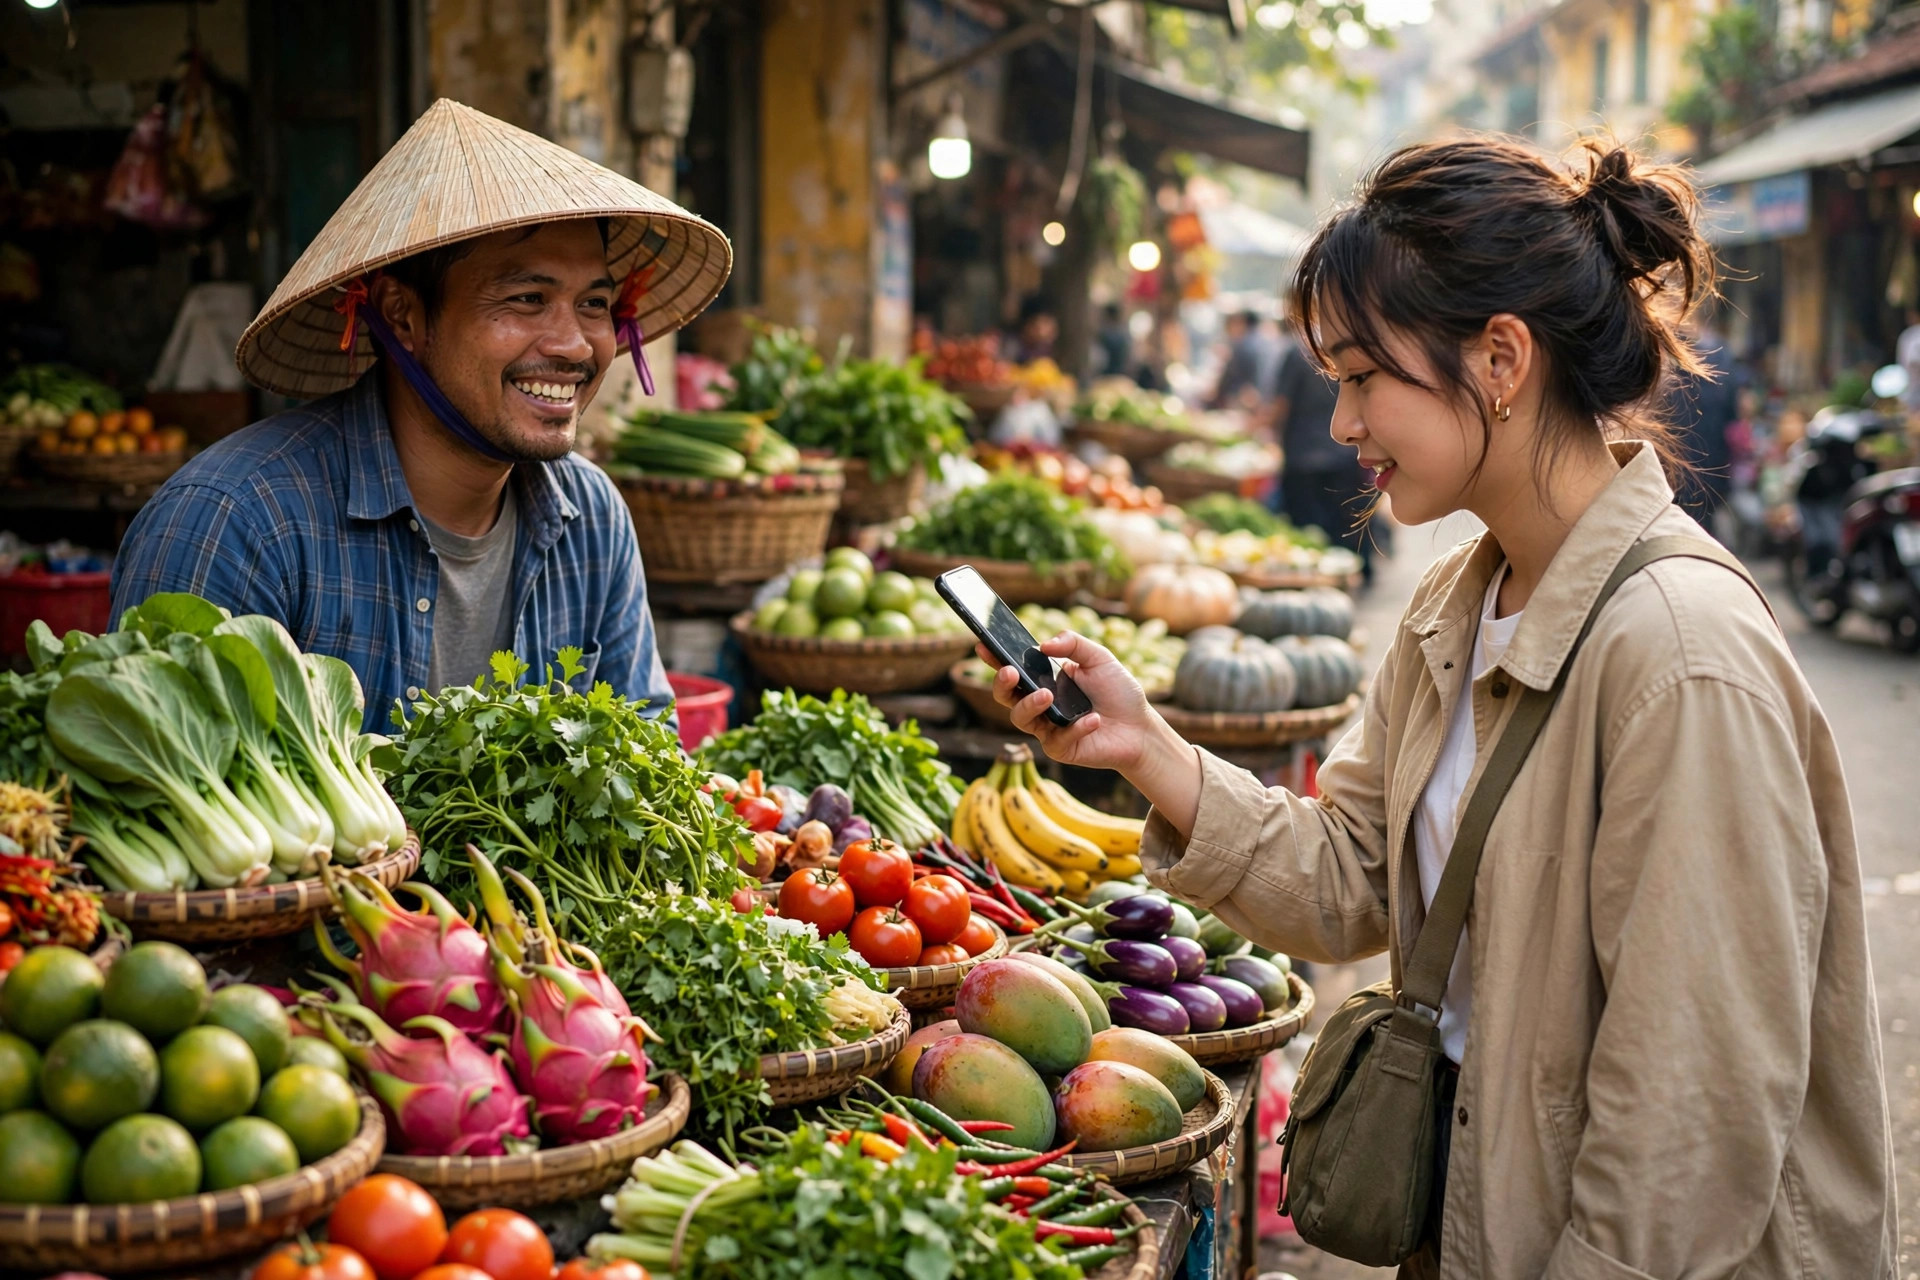
On a wet-market morning in Hanoi, a vegetable seller closes a sale without touching a single banknote. The customer points a phone at a small printed square taped to the stall, a soft beep confirms the payment, and both move on. That square is the most ordinary piece of technology in Vietnam today, and QR payments in Vietnam have spread so far, so fast, that they skipped an entire stage of financial history: the plastic card.
Most countries moved from cash to cards, then from cards to phones. Vietnam went from cash to phones and largely left the card step behind. There was no decade of swiping at every counter, no forest of card machines in small shops, and no monthly rental fee standing between a street vendor and a cashless sale. The phone in the customer’s pocket became the terminal, and a printed code became the till.
A printed square replaced the card machine
At the centre of the shift is VietQR, the shared QR payment system run by the National Payment Corporation of Vietnam, known as NAPAS. Before VietQR, each bank and wallet had its own code, and a shop that wanted to accept them all needed a small gallery of printed squares. VietQR gave banks one common standard, so a single code at a stall works with the banking app of almost any customer who walks up.
The economics explain the speed. A card terminal costs money to buy or rent, needs a power socket and a network connection, and takes a cut of every sale. A QR code costs almost nothing: a vendor prints it, tapes it to the counter, and links it to a bank account. NAPAS, partner banks and payment intermediaries have built the system outward from there, adding VietQRPay for domestic transfers and VietQRGlobal for cross-border payments, so the same scan can also serve a foreign visitor or an online order.
The result is visible everywhere commerce happens in Vietnam: supermarkets and shopping malls, certainly, but also noodle stalls, corner shops, late-night food carts and the motorbike-side drink sellers who set up wherever people gather. The payment infrastructure did not wait for small businesses to formalise or grow. It met them where they were.
Why the smallest sellers moved first
In most countries, new payment technology reaches big retailers first and trickles down over years. In Vietnam the order ran the other way, because the smallest sellers had the most to gain and the least to lose. Cash is slow at a busy stall: counting notes, finding change, and keeping a float of small bills eats time at exactly the moment customers are queuing. A scan takes seconds, there is no change to find, and the money lands in the account with a record attached.
That record matters more than it looks. A vendor who can see the day’s sales on a phone screen can track what sold, spot a quiet day early, and show a bank a real history of income when asking for a loan. Tax officials have made the same point from the other side: digital payments reduce manual bookkeeping for small vendors and make daily cash flow easier to follow, which raises transparency across the whole market.
The scale is now large. With close to 90 million mobile banking accounts active in the country, almost any micro-business can join the system overnight. NAPAS reported that in the first ten months of 2025, VietQR transactions rose 52 percent in volume and 85 percent in value compared with the same period a year earlier. Each of those beeps at a market stall is a small piece of the country’s digital economy, and the country has made that economy a stated priority for 2025 to 2030.
What changed for the person paying
For customers, the habit formed quickly because it removed small frictions rather than adding new ones. There is no need to carry exact change for a 15,000-dong coffee, no wallet to open at a food cart, and no queue held up by a card machine searching for a signal. The phone most people already carry does the whole job.
It also changed how people think about small spending. When every payment leaves a trace in a banking app, the week’s spending becomes visible in a way cash never was. That visibility is not always welcome, but for many households it has made budgeting less of a guessing game. And for visitors, cross-border QR links mean a tourist can pay a street vendor with a home-country app, a convenience that would have been unthinkable when cash was the only option at a stall.
The comparison with other countries is instructive. India’s UPI system followed a similar path, building a shared real-time payment layer that let phones leapfrog cards, and our companion piece on India’s instant payment system explains how that worked. Vietnam’s version is smaller and quieter, but the logic is the same: agree on one standard, make joining it nearly free, and let the smallest sellers lead.
The limits of a square of pixels
None of this means cash has disappeared, and a QR code has real limits. It needs a charged phone and a mobile signal, two things that fail often enough in rural areas and during storms. Older vendors and customers who never adopted smartphones can find themselves locked out of stalls that have gone fully cashless, and a seller who loses a phone can lose the day’s takings along with it.
Fraud has followed the money, too. A printed code is easy to swap: criminals have pasted their own QR stickers over a vendor’s genuine code, diverting payments to their own accounts. Banks and NAPAS have responded with named, verified codes and confirmation screens that show the recipient’s name before the payer confirms, but the defence depends on customers actually reading that screen before they tap.
There is also a quiet cost to convenience. When every transaction is recorded, a vendor’s entire business becomes visible to banks, tax offices and payment companies. Most sellers accept that trade as the price of faster sales and easier credit, but it is a real shift from the anonymity of cash, and it deserves to be named rather than waved away.
What this means
QR payments in Vietnam show that a country does not have to walk every step of the path other countries walked. When the infrastructure is cheap, shared and open to the smallest seller, adoption can run from the bottom up instead of the top down. The lesson travels well beyond payments: the same pattern — one common standard, near-zero cost of joining, and a tool that fits the way people already live — is visible in Vietnam’s digital identity system and in the once-only government services Estonia built on its X-Road data exchange. Vietnam skipped the card. The interesting question now is what else it can skip.