Data centers Vietnam is building right now are the plain, windowless buildings where the country’s digital life actually lives. Every QR payment, every video call, every e-invoice and every livestream sale passes through racks of servers in a data center somewhere. For years, much of that computing happened abroad, in Singapore or Hong Kong, because Vietnam had too few facilities of its own. That is changing fast. By August 2025 the country hosted about 41 operational data centers with roughly 221 megawatts of combined IT power, and the pipeline of announced, planned and under-construction facilities already exceeds 500 megawatts of additional capacity. The buildings behind the cloud are becoming a major industry of their own.
What a data center actually is
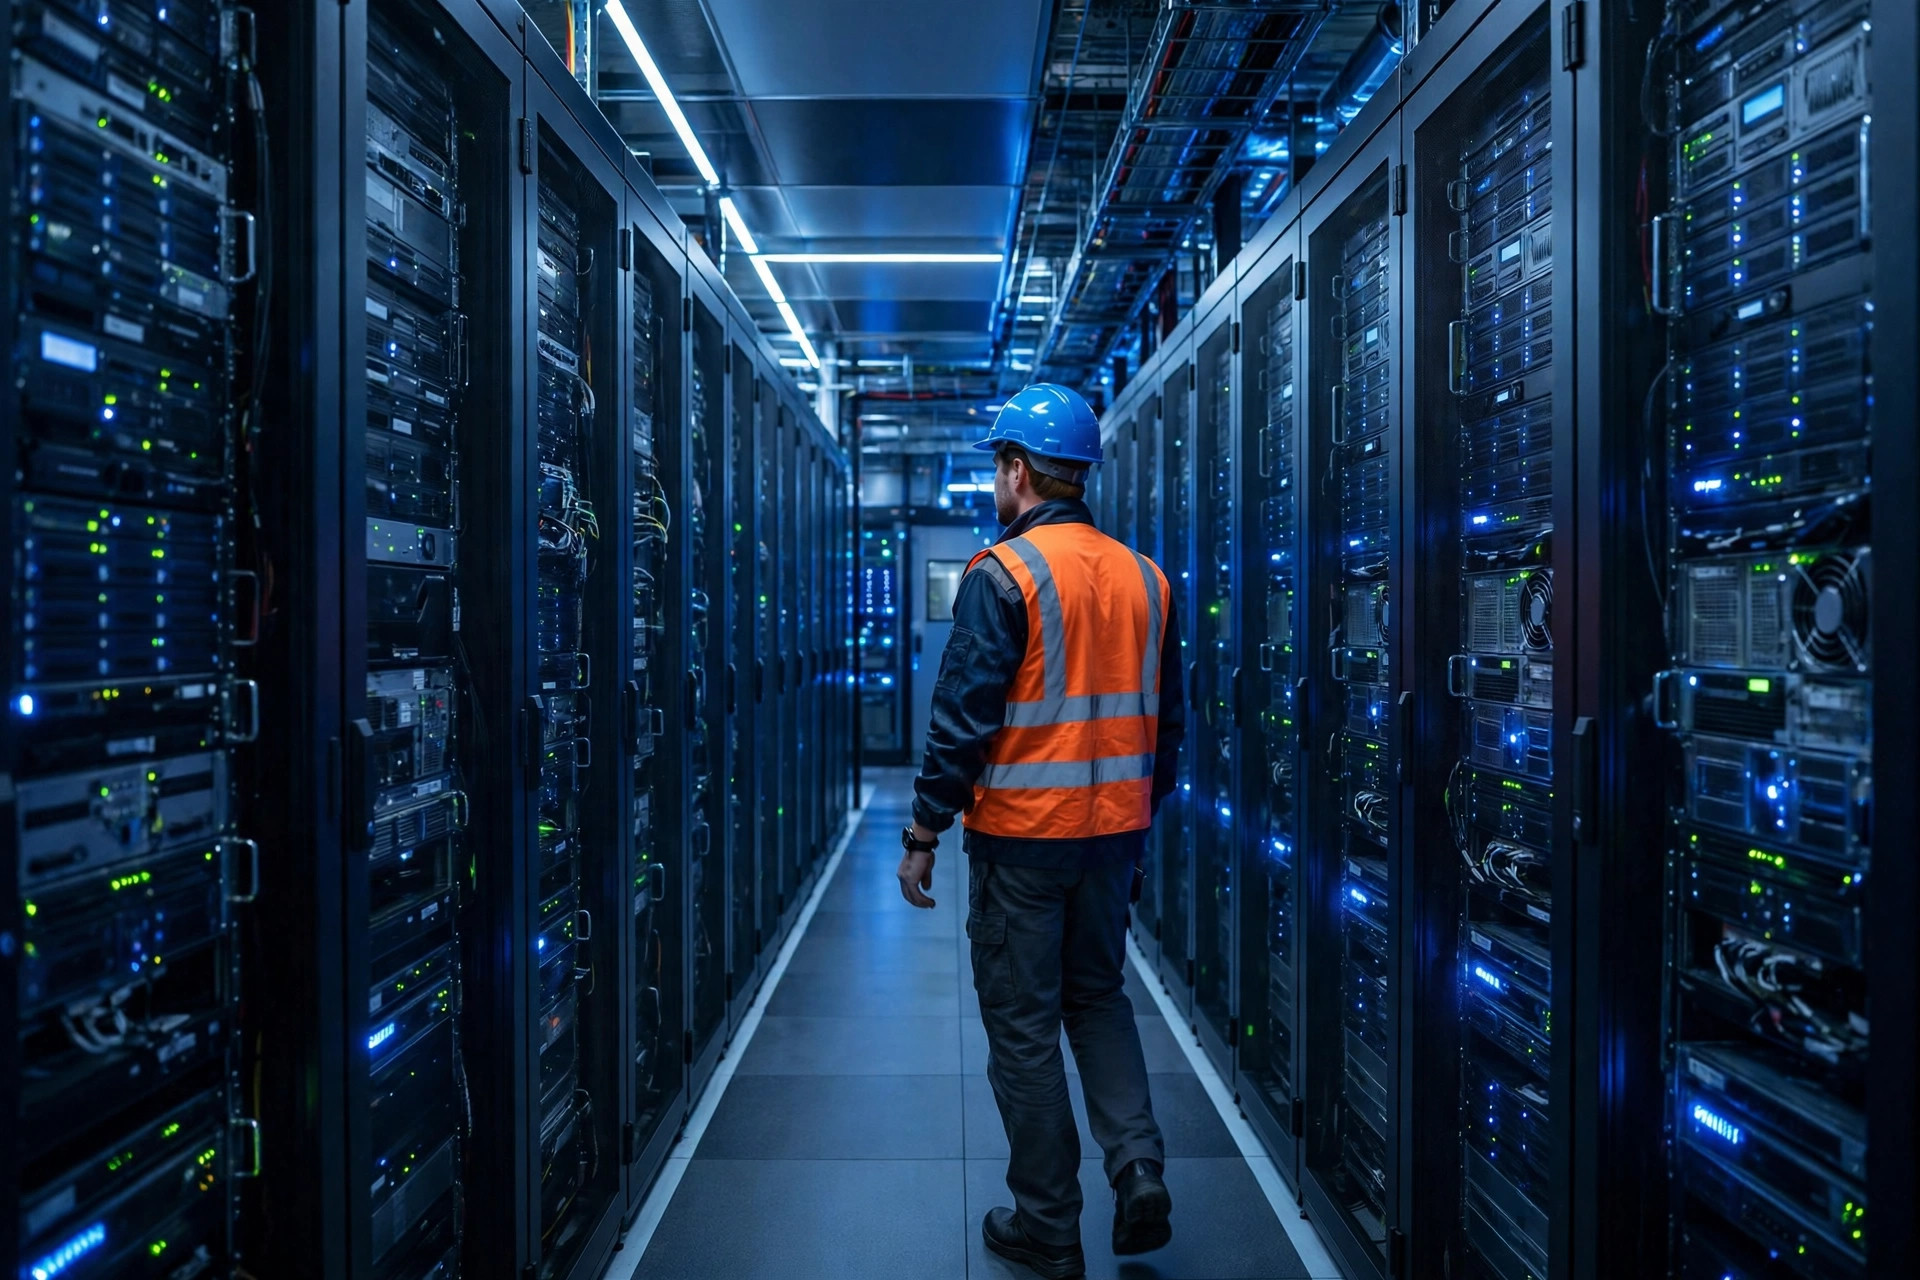
Strip away the mystique and a data center is a warehouse for computers, built to keep them powered, cool and connected without interruption. Rows of racks hold servers, storage and networking equipment. Uninterruptible power supplies and diesel generators take over if the grid fails. Air conditioning — or increasingly liquid cooling — carries away the heat the servers produce. Fibre connections link the building to the rest of the internet. Security is physical as well as digital: fences, guards, cameras and biometric doors, because the data inside belongs to banks, hospitals, government agencies and millions of ordinary users.
The scale varies enormously. A small colocation facility might host a few hundred racks for local businesses. A hyperscale campus, the kind built by global cloud companies, can hold tens of thousands of servers and consume as much electricity as a small town. Vietnam’s market is still dominated by smaller and medium-sized facilities, but hyperscale projects are arriving, and analysts at Mordor Intelligence estimate the hyperscale segment alone could grow from 2.45 billion US dollars in 2025 to 6.76 billion by 2031. The distinction matters because hyperscale customers — the big cloud platforms and AI companies — bring the largest investments and the most demanding requirements.
Where Vietnam’s data centers sit
Most of Vietnam’s data centers cluster around the two big cities, and for a good reason: that is where the fibre lands and where the customers are. Southern Vietnam holds the largest installed base, thanks to its access to the submarine cables that come ashore at Vung Tau, while northern Vietnam is the fastest-growing region, driven by government demand and proximity to policy makers. Ho Chi Minh City and Hanoi dominate, with Da Nang emerging as a secondary hub for central Vietnam.
The geography is shifting as the industry grows. Land and power are cheaper outside the big cities, and operators are looking at industrial provinces such as Binh Duong, Bac Ninh and Hai Phong, where large campuses can be built near factories that need them. The pattern follows the same logic as the undersea cables that land on Vietnam’s coast: connectivity first, then everything else. A data center is only as useful as its connection to the internet, and the best-connected sites remain the most valuable.
Who is building them
For years the builders were Vietnam’s own telecom giants. Viettel IDC, the data center arm of Viettel, is the largest domestic operator, and its 140-megawatt campus in Ho Chi Minh City is the first domestic site to break the 100-megawatt threshold. VNPT, FPT and CMC run their own facilities and cloud platforms, and VNG Cloud serves the country’s internet and gaming industries. These companies built the first generation of Vietnamese data centers, and they still operate most of the capacity in service today.
The second wave is different: it is bigger, better funded and often foreign-backed. Saigon Asset Management has committed 1.5 billion US dollars for a 150-megawatt campus in Binh Duong province. Regional momentum is strong: a Cushman & Wakefield report cited by Nhan Dan notes that across Asia-Pacific, 4.8 gigawatts of data center capacity is under construction and 21.7 gigawatts in planning, while colocation vacancy rates have fallen as demand absorbs new supply. Foreign investors can now own data centers outright, following ownership liberalisation, and global hyperscalers are entering the market directly rather than renting space from local operators. The result is a construction boom: total national IT capacity is projected to rise from about 525 megawatts in 2025 to roughly 950 megawatts by 2030.
Power and cooling in a tropical country
Building a data center in Vietnam means fighting two things the climate provides in abundance: heat and humidity. Servers generate enormous amounts of heat, and in a country where the temperature rarely falls below 25 degrees, cooling is the largest operating cost after electricity itself. Traditional air cooling is giving way to more efficient designs — hot-aisle containment, free cooling at night, and liquid cooling that carries heat away from the densest racks directly. Rack densities are rising, with some cabinets now drawing 40 kilowatts or more, which makes efficient cooling a competitive advantage rather than a detail.
Power is the bigger constraint. Vietnam’s national energy plans aim to roughly double generation capacity to 155 gigawatts by 2030, but data centers need power that is not only plentiful but reliable, with backup systems that can take over in seconds. Operators are increasingly pairing their campuses with renewable energy and battery storage, both to secure supply and to meet the sustainability requirements of their largest customers. A data center that cannot prove its power is clean and reliable will struggle to win hyperscale tenants, however cheap its land is.
Why the rules pushed demand home
Policy has been a powerful accelerant. Decree 53 of 2022, which implements the Cybersecurity Law, requires certain categories of data to be stored inside Vietnam. That single rule created a strong reason for banks, e-commerce platforms and foreign technology companies to host their Vietnamese data in Vietnamese facilities instead of Singapore. The national digital transformation programme added a cloud-first push for government services, and the growth of 5G is generating new demand for edge facilities that sit close to users and devices.
The effect is visible in the market: demand for domestic capacity is rising faster than operators can build it, and the vacancy rate for colocation space has been falling even as new supply comes online. For businesses, the practical consequence is that the cloud services they rent increasingly run on servers inside Vietnam, which means lower latency, easier compliance and data that stays under Vietnamese law.
What this means
Data centers are the least glamorous part of the digital economy and one of the most important. Vietnam spent years as a consumer of other countries’ computing infrastructure; it is now building its own, at a pace that surprises even industry watchers. The challenges are real — power supply, tropical cooling, and the need for skilled engineers to run facilities that never sleep. But the direction is set: more capacity, larger campuses, and foreign investment joining domestic operators. The next time a payment clears in a second or a video loads without buffering, the credit belongs partly to a windowless building on the edge of a Vietnamese city, full of humming racks and cold air, doing exactly what it was built to do.
Sources
- Invest Vietnam — Vietnam Data Center Market 2026: Growth, Trends, and Key Players (41 facilities, 221 MW, 500+ MW pipeline)
- Mordor Intelligence — Vietnam Hyperscale Data Center Market (US$2.45 billion in 2025, US$6.76 billion by 2031)
- Research and Markets — Vietnam Data Center Server Market (Viettel 140 MW campus, Saigon Asset Management 150 MW Binh Duong)
- Nhan Dan — AI and data centre investment surge advances into Viet Nam (Cushman & Wakefield APAC H1 2026 update)