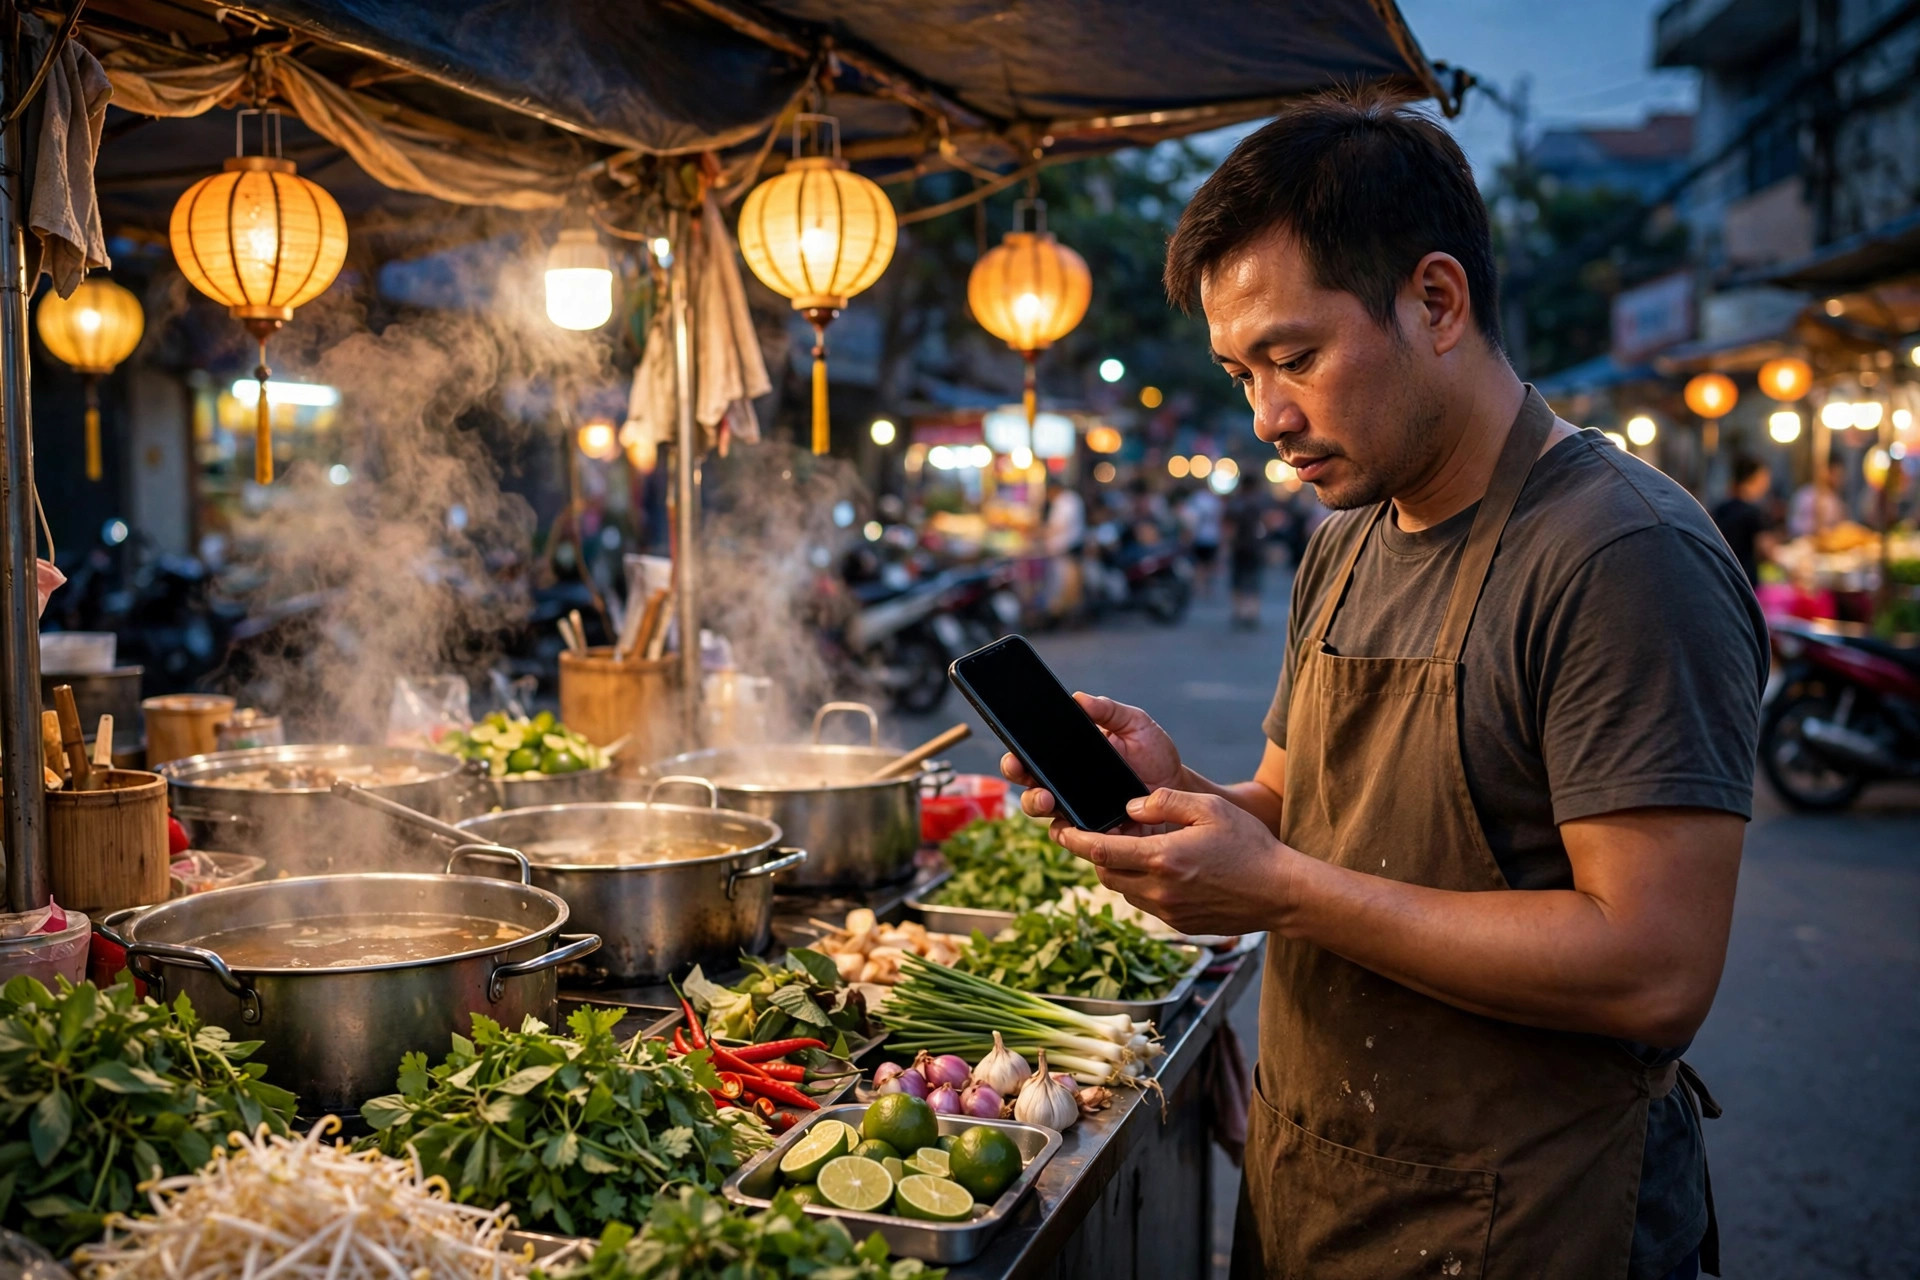
For a small business owner in Vietnam, the bank used to be a building with a queue. Today, digital banking for small businesses in Vietnam fits in a pocket: an account that opens on a phone, a QR code that takes payment, a loan approved on sales data instead of a pile of paper, and a dashboard that shows where the money went. A bank that works at the speed of a phone call is no longer a luxury. It is the back office a small firm never had.
The account that opens itself
Opening a business account used to mean a morning at a branch with a folder of documents. Now the largest Vietnamese banks let a business open an account online, with identity checks done by phone camera and chip-based ID card. Techcombank’s business account, for example, can be opened online, comes with QR payment acceptance, batch payments for salaries and suppliers, and a central dashboard for tracking transactions. Vietcombank’s Digibank for household businesses goes a step further: one app, two roles, letting an owner switch between a personal account and a business account so the two streams of money stay separate.
A dedicated business account changes the answer from a guess to a number — and a clean money trail is the first thing a lender, a supplier or a platform asks to see.
Getting paid without touching cash
The most visible part of digital banking for small firms is the QR code on the counter. A customer scans, pays, and the shop hears a chime. The State Bank of Vietnam reported that QR code payments grew 61.6 percent in volume and 150 percent in value in the first nine months of 2025 compared with the same period in 2024, and the average day now sees around 15 million QR transactions, according to the national payment switch NAPAS.
Banks have built whole toolkits around that one code. Techcombank gives small retailers a store QR code for each sales point, a speaker or voice announcement that calls out each payment so the cashier hears it, and a feature to share transaction notifications with staff. Vietcombank’s OneQR lets a shop accept payments from domestic and foreign customers with a single code, and its cross-border QR links now cover Thailand, Laos, Cambodia, China, South Korea and Singapore. For a shop near a tourist street, that means a visitor from Bangkok can pay with their home banking app, and the money lands in the shop’s account. A phone can also become a card terminal: softPOS turns the owner’s handset into a machine that accepts contactless cards, with no hardware to buy.
Borrowing on data, not paperwork
The hardest problem for a small business has always been borrowing. A bank wants collateral and three years of audited accounts; a small trader has neither. Digital banking is changing what counts as proof. Because payments now flow through the account, the bank can see real revenue, day by day, and lend against it.
Techcombank’s offering for household businesses shows the new shape of it: a ShopCash overdraft with a pre-approved limit of up to 1 billion dong, flexible repayment with no early repayment fee, and unsecured instalment loans of up to 1 billion dong over 3 to 36 months, plus larger secured credit for bigger firms. The limits are the bank’s published figures, and any real loan still depends on the bank’s assessment, but the principle is what matters: the decision is based on the business’s actual money flow, visible in the account, rather than on a folder of paper.
Cash flow you can actually see
Most small businesses do not fail because they make no money. They fail because the money arrives at the wrong time — a big supplier bill lands the week before the big customer pays. Digital banking turns that guesswork into a picture. Revenue charts show takings by day and week, so the owner can see that weekends carry the month. Scheduled payments handle rent, electricity and salaries without a trip to the bank. Some business accounts now pay interest automatically on idle balances.
The same systems connect to the rest of the business. Sales software can issue electronic invoices and send the data to the tax office; the bank account can link to the eTax mobile app so the owner declares and pays tax from the same phone. BIDV has taken this furthest for larger firms, with platforms that plug into a company’s accounting system, manage supply-chain finance and handle trade documents online. The pattern is the same at every size: the bank stops being a place you visit and becomes a set of tools inside the software the business already uses.
What to watch before you switch
Digital banking is not free of risk, and a small business should choose with its eyes open. Fees vary widely between banks and packages, and a free account can become expensive through transaction charges, card fees and loan interest — read the schedule before signing. Security matters more than ever: the business phone now holds the keys to the money, so it needs a lock screen, a separate user profile for staff, and transaction limits that match the real business. Scams targeting small traders are common, and a bank will never ask for a one-time password by phone.
There is also a practical question of dependence. A shop whose payments, invoices and loans all run through one bank’s app is in trouble if that app goes down on a busy Saturday. Keeping a second payment option — cash, another bank’s QR, or an e-wallet — costs little and saves the day when the main system fails.
What this means
Digital banking has given Vietnam’s small businesses something they never had before: a back office. An account that opens in minutes, a QR code that records every sale, a loan judged on real revenue, and a dashboard that shows the cash position before the owner spends it. The banks that win this market will be the ones whose tools fit inside a trader’s working day, not the ones with the most branches. For the small business owner, the test is simple: if the bank saves an hour a day and shows you where the money is, keep it. If it only adds fees and notifications, find another.
Sources
- Vietstock — More connected than ever, banks integrate into every economic touchpoint
- Vietnam.vn — Techcombank implements financial solutions to support household businesses
- Techcombank — Flexible, fast and convenient business current accounts
- Vietnam.vn — Vietcombank is committed to developing inclusive digital finance
- Vietnam.vn — Digital payments are booming, with transactions via QR code increasing by over 150%
- How Vietnam’s QR payments skipped the card era
- E-invoicing for small businesses in Vietnam, explained
- How Estonia built a once-only government on X-Road